


Swim Spas
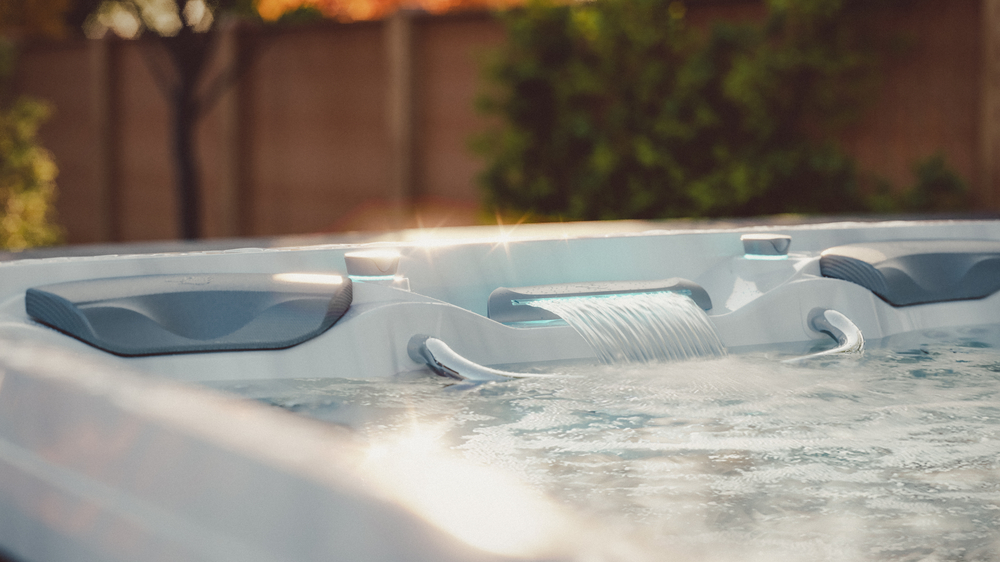
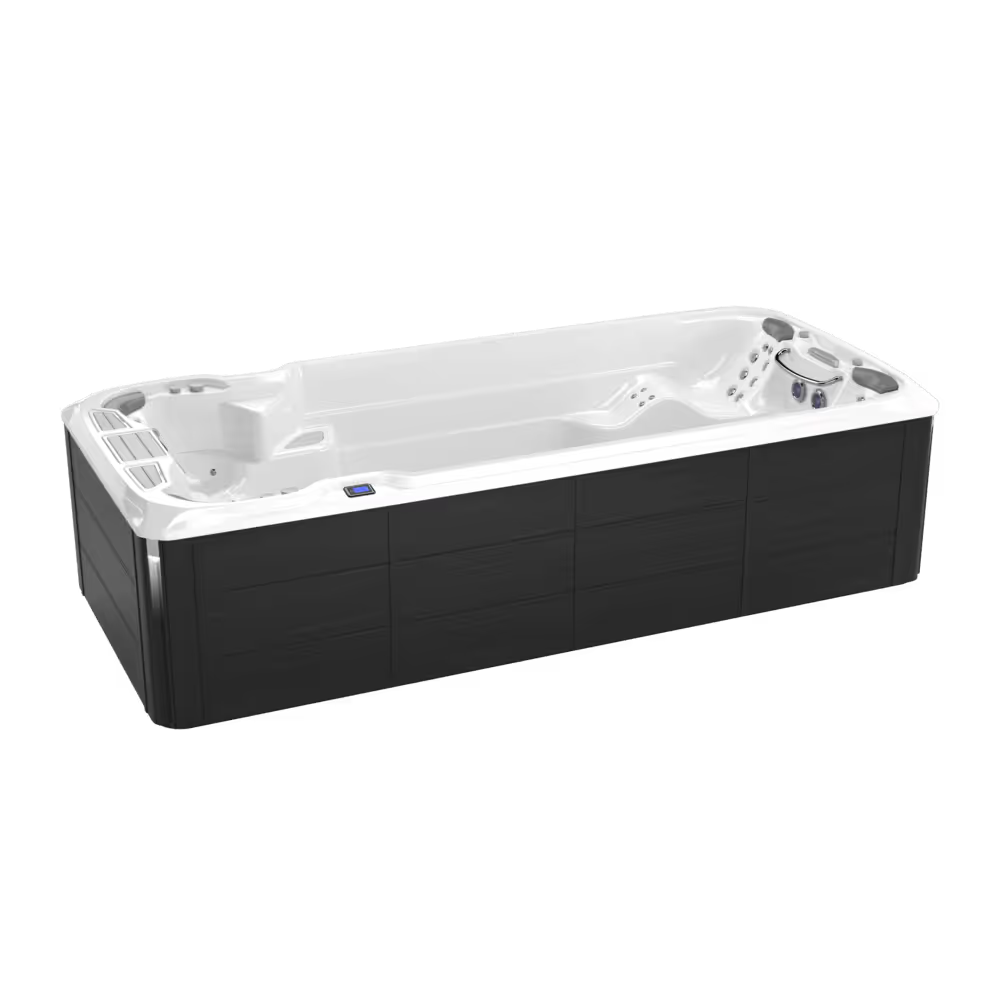
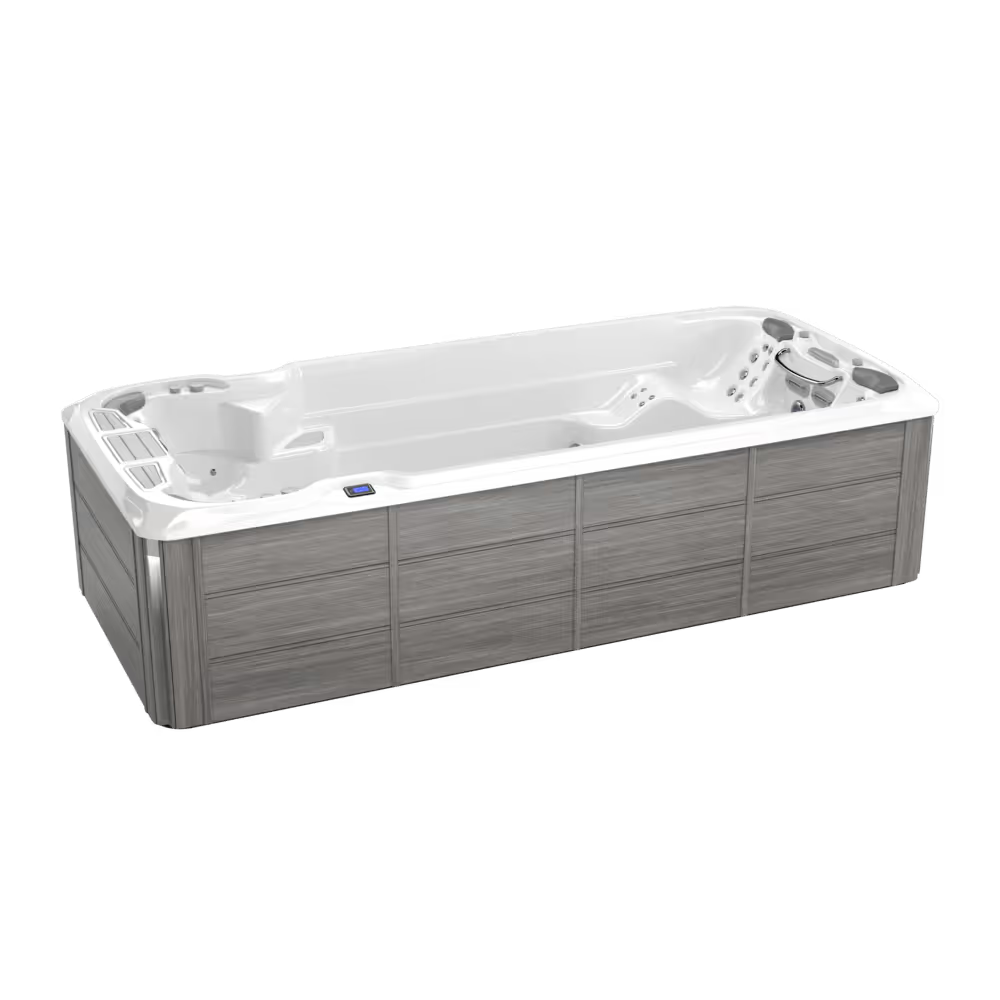
Sundance 17 Stream™
Seating:
4-6
Seats
Therapy & Recovery
SmartTub System
$$$$$
MSRP$43499
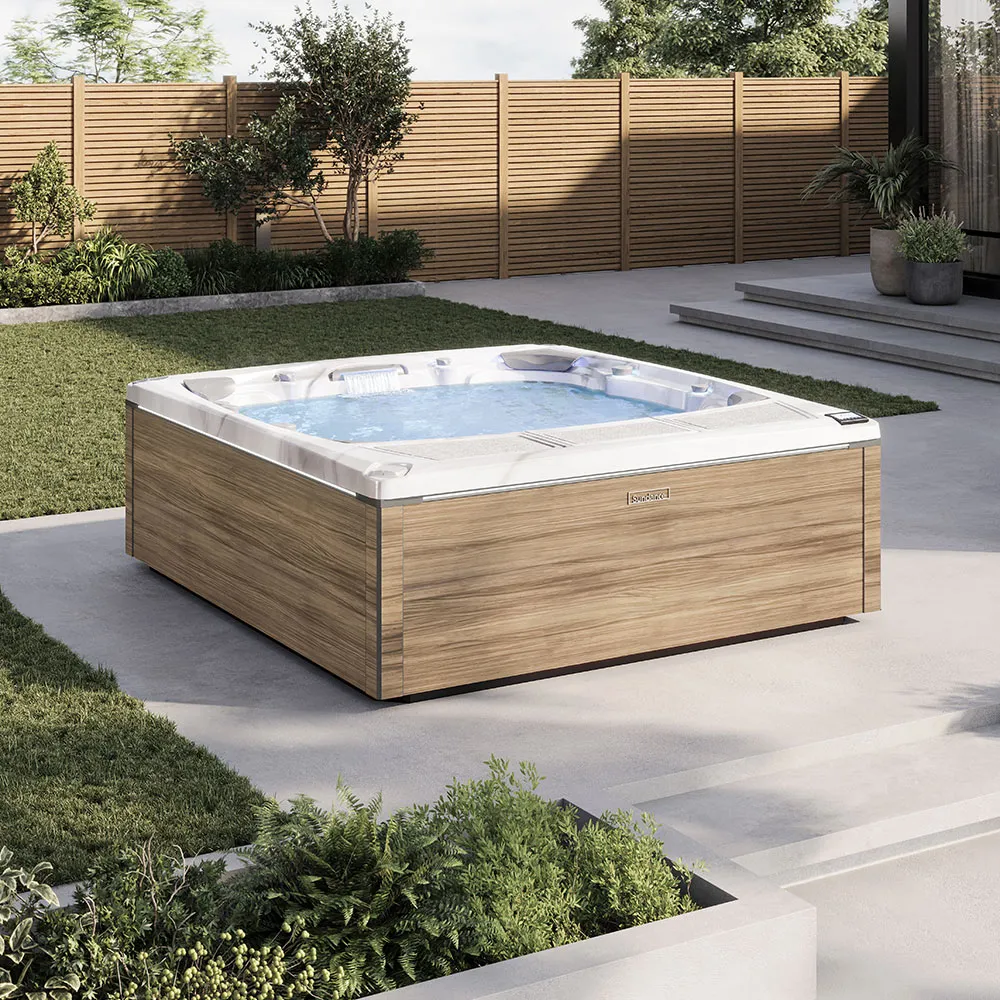
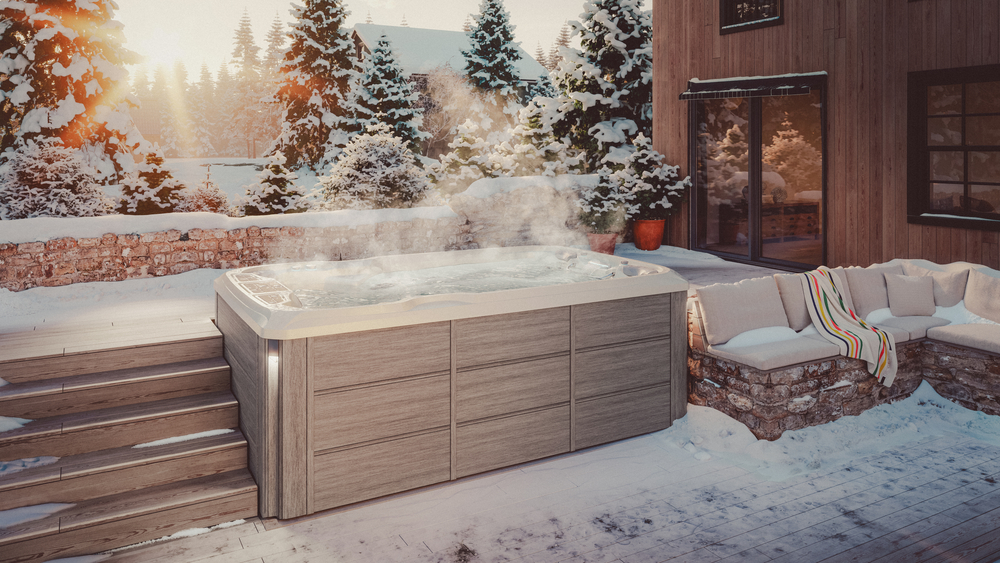
Make a bold statement with a superbly crafted spa, rich with features that are ideal for entertaining or simply relaxing.

Our best-selling spas offer an ideal balance of advanced features, premium comfort, and transformative hydrotherapy.

All the right features for all your best moments, at a value that makes it all possible. Now it's time to make it all happen.
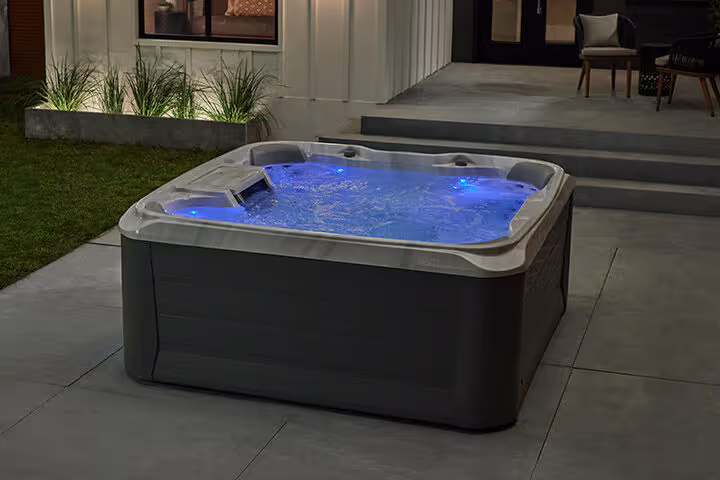
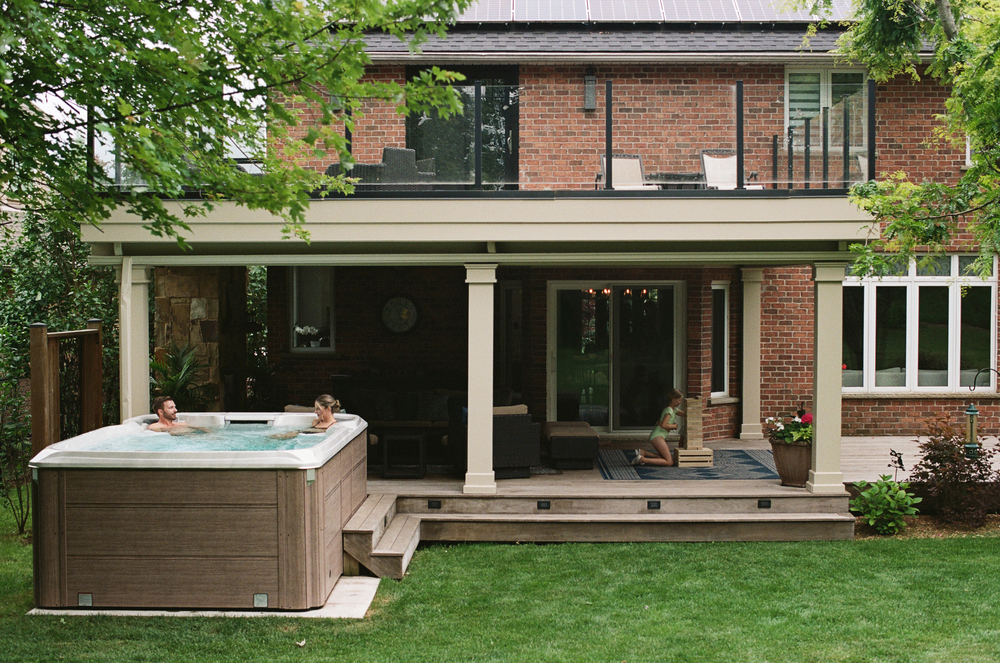
It's easy to love the 680 Series spa for all the fun and relaxing moments, but you'll also appreciate its superior durability and value.
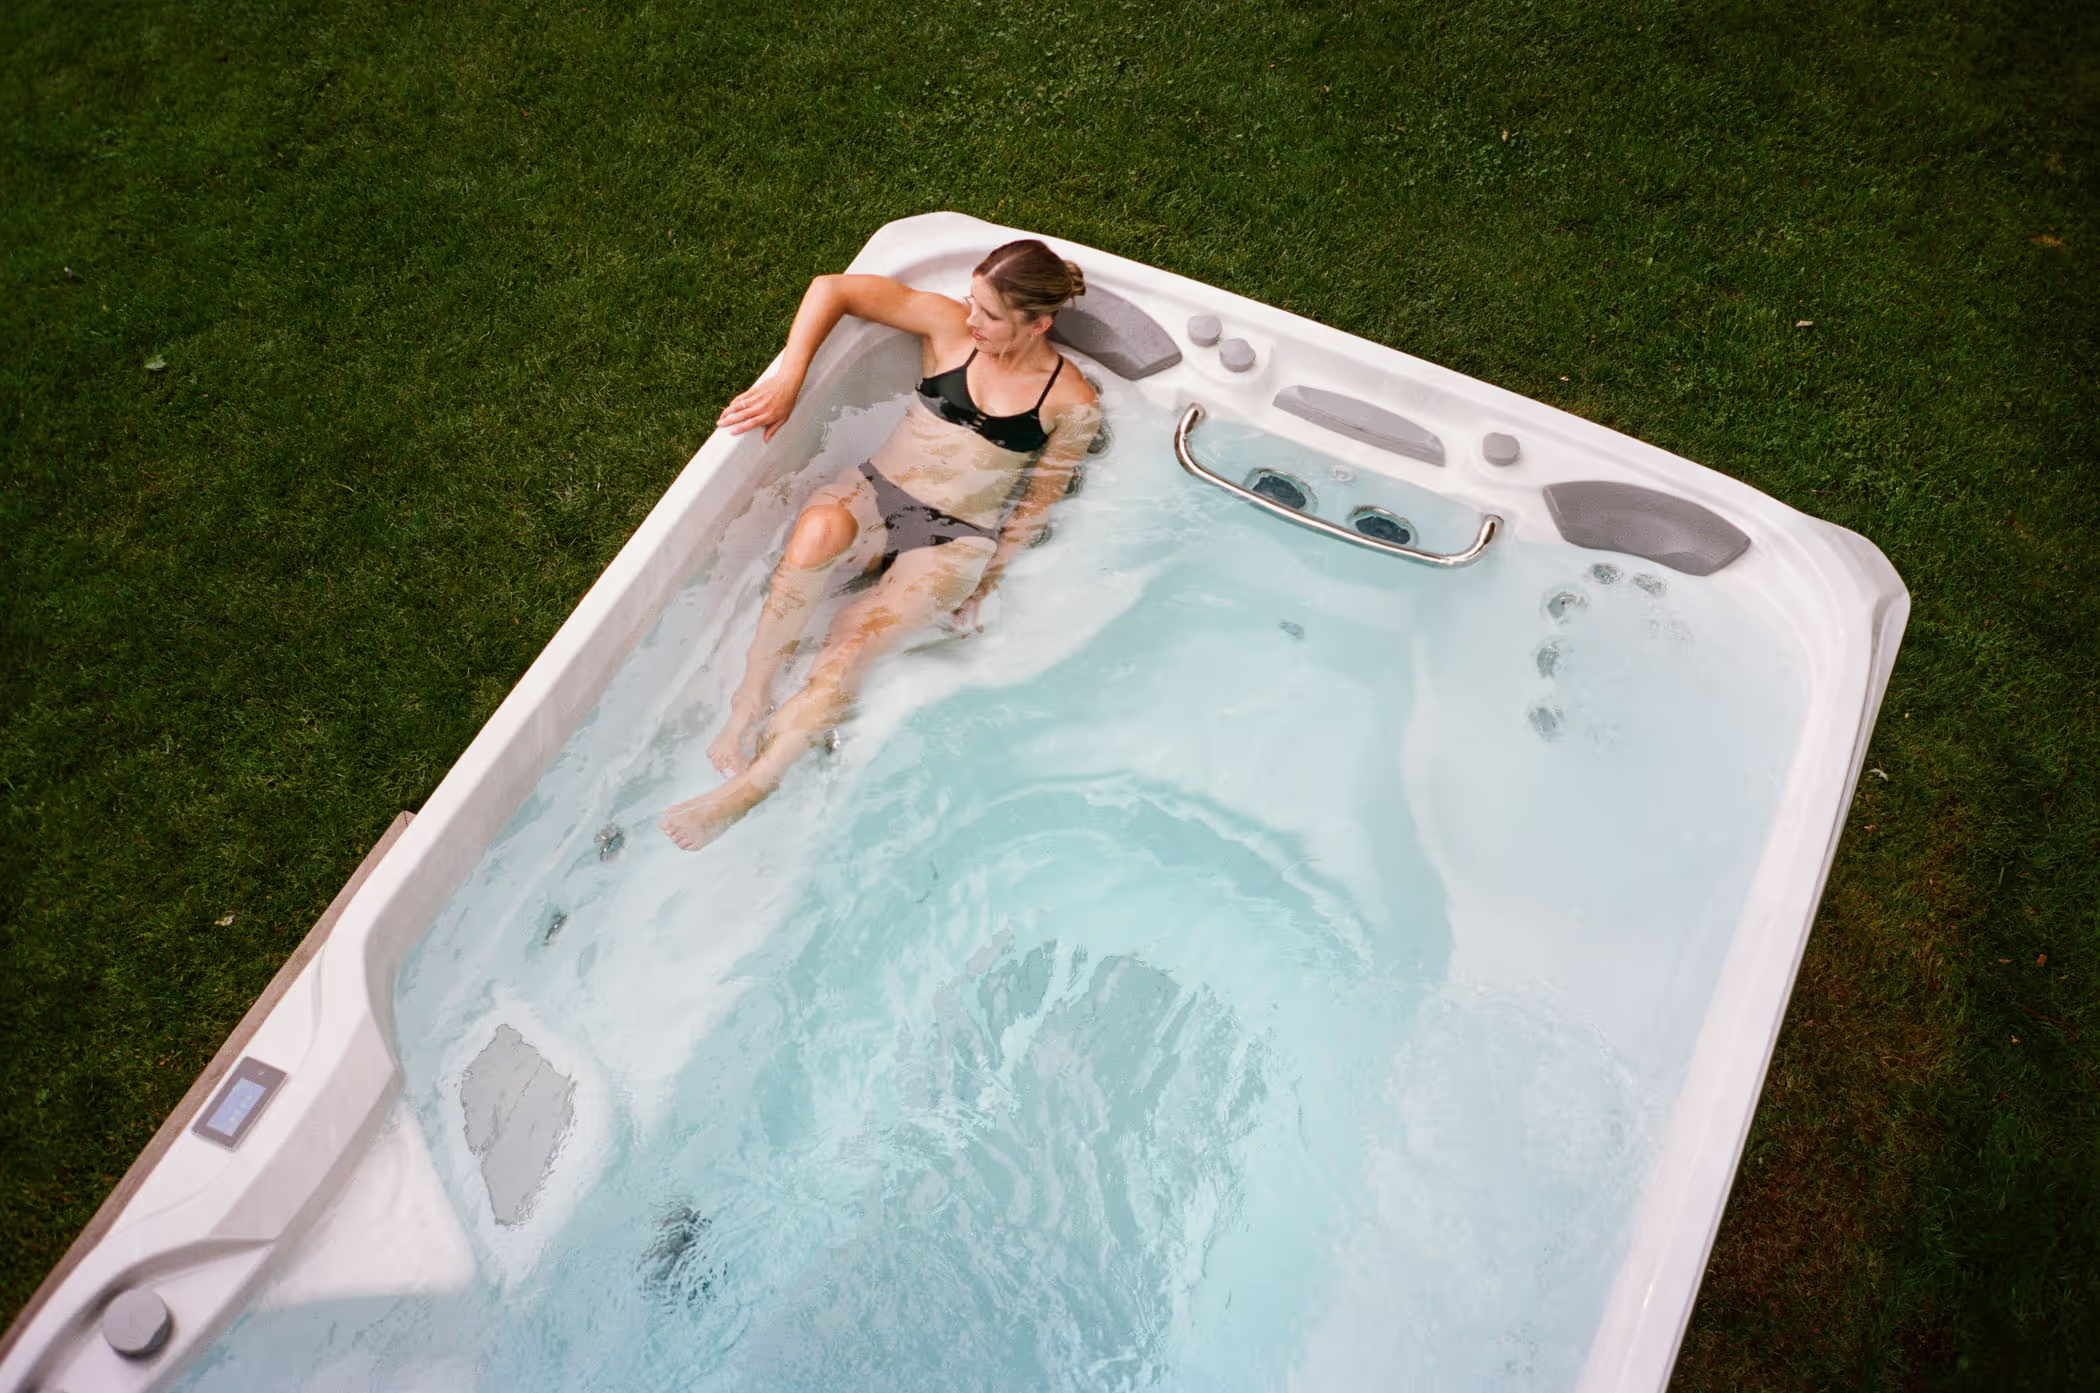
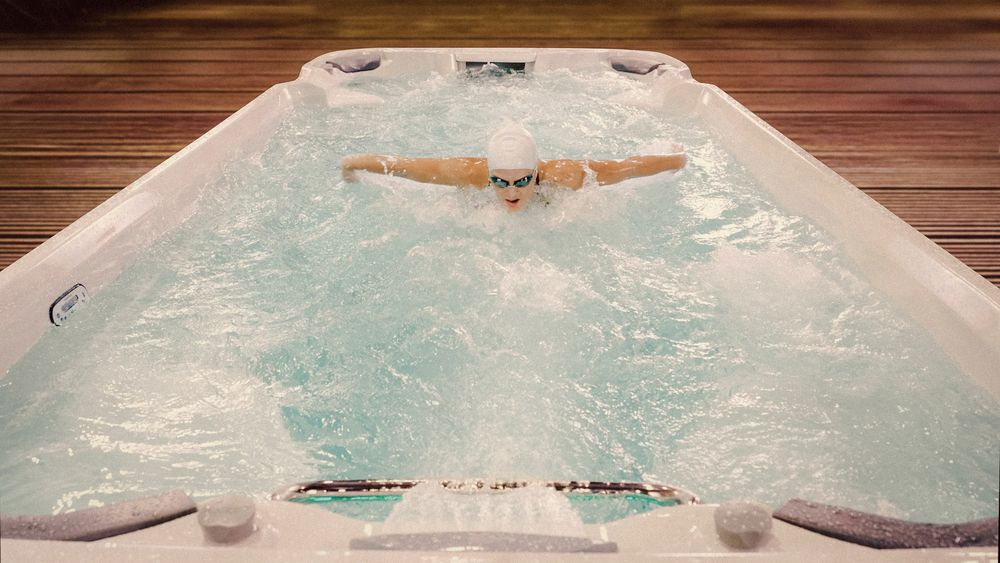
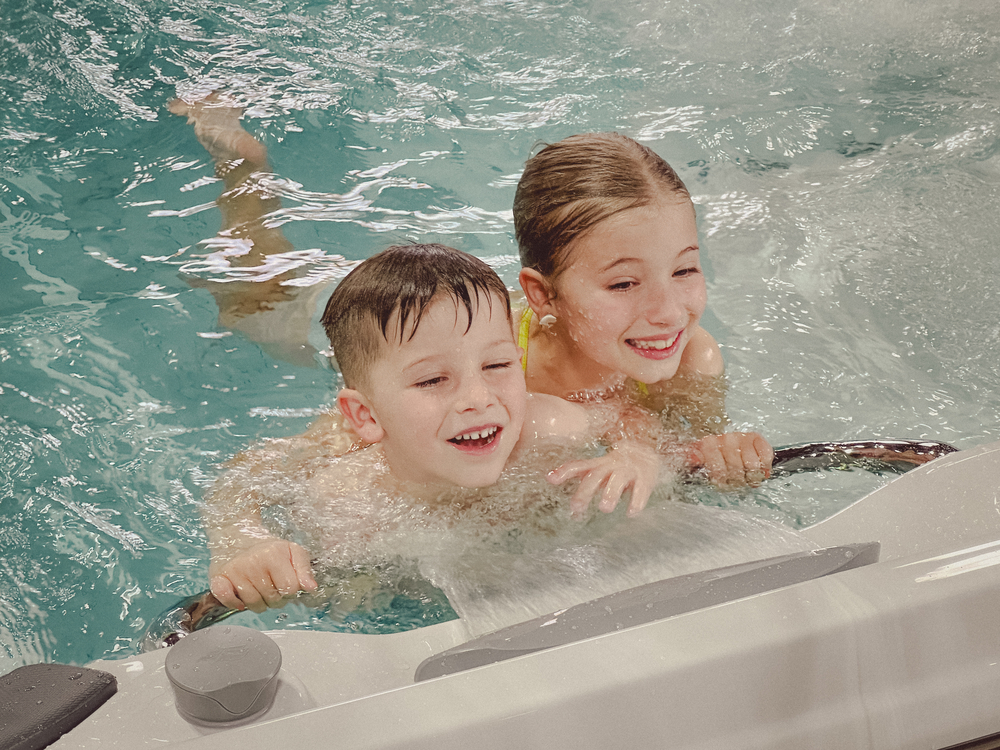
It's easy to love a swim spa for the daily movement and water time it brings, but you'll also appreciate how seamlessly it fits an active life at home.

Every Sundance® spa is built to maximize relaxation with features that make spa ownership a breeze so you can enjoy your new spa with confidence.
Find Your Spa
Explore Sundance models to find the perfect spa for you.


Erica Moir is vice president of design and advanced technologies at Jacuzzi Group, where she leads product innovation across spa and bath categories. With more than 22 years at the company, she has held leadership roles in marketing, product design, and development across North America and Europe. Moir is passionate about driving creative, sustainable solutions that enhance both product performance and customer experience. She holds degrees in industrial and product design from Fanshawe College and fine arts from the University of Windsor.
When you’re ready to invest in a swim spa, the $15,000 to $40,000 price tag might seem daunting. However, with the right financing approach, you can transform this significant investment into manageable monthly payments that fit your budget. Unlike traditional swimming pool installations that can cost $40,000 to $70,000 and take months to complete, swim spas offer a more accessible path to year-round aquatic fitness and relaxation.
Today, over 60% of swim spa purchases are financed rather than paid in cash, making affordable monthly payments a decisive factor for most buyers. Whether you’re considering dealership financing, personal loans, or home equity options, understanding your choices will help you make an informed decision that aligns with your financial goals.
Swim spas represent a significant investment, with pricing that varies considerably based on features and quality. Basic models start around $15,000, while premium units with advanced hydrotherapy features, superior swim jet technology, and energy-efficient systems can exceed $40,000. The majority of mid-market offerings fall in the $25,000–$30,000 bracket, providing a good balance of features and value.
When you compare this to traditional pools, the value proposition becomes clear. In-ground pools typically cost between $40,000 and $70,000 to install, often requiring months of construction and higher ongoing maintenance costs. Swim spas can be installed in just 1-2 days, whether above ground or semi-recessed, making them a more practical option for many homeowners.
The installation process for swim spas is remarkably streamlined compared to traditional pool construction. While you’ll need site preparation such as a concrete pad and electrical work, these requirements are far less invasive and expensive than the extensive groundwork required for pools. This means you can start enjoying your investment much faster, without the hassle of lengthy construction projects.
Beyond the initial purchase, swim spas offer excellent long-term value through energy efficiency and potential property value increases. Many models feature advanced insulation and heating systems that keep operating costs manageable year-round. When integrated with a deck or patio design, swim spas can enhance your property value, though this effect varies by location and buyer preferences.
Dealership financing, including programs offered by brands like Sundance Spas, provides one of the most convenient paths to swim spa ownership. These financing programs are designed to be hassle free, often partnering with specialized lenders to offer quick approvals that can happen within minutes. The simple application process typically requires only basic documentation such as income verification and a credit check.
This convenience factor cannot be overstated when you’re ready to make a purchase decision. Rather than shopping around to multiple banks or credit unions, you can complete your entire transaction in one location, from selecting your spa to finalizing your loan terms.
Dealership financing offers flexible terms that can accommodate various financial situations. Interest rates typically range from 0% during promotional periods to around 15% APR for standard financing. The most attractive deals often feature 0% APR for 24–72 months, though these promotional rates are usually reserved for customers with approved credit scores of 700 or higher.
Loan terms are designed with flexibility in mind, typically spanning 12 to 84 months. This range allows you to choose a payment structure that works best for your budget. While longer terms mean lower monthly payments, they also result in higher total interest costs, so it’s important to find the right balance for your financial situation.
Manufacturers and dealers periodically offer special financing programs that can provide significant savings. These might include:
These offers can make a substantial difference in your total cost, so it’s worth timing your purchase to take advantage of promotional periods.
Personal loans from banks or credit unions represent another popular financing option, particularly if dealership terms aren’t favorable for your situation. These unsecured loans don’t require collateral, making approval dependent primarily on your credit history, income, and debt-to-income ratio.
The main advantage of personal loans lies in their predictable structure. Fixed interest rates mean your monthly payment remains constant throughout the loan term, making budgeting easier and protecting you from rate fluctuations that can affect variable-rate products.
Most personal loan programs require a minimum credit score of 660 or higher, with the best rates reserved for borrowers with scores above 700. Interest rates typically range from 6% to 24% APR, with your specific rate determined by your creditworthiness and the lender’s assessment of risk.
The application process usually takes several days and requires more comprehensive documentation than dealership financing. You’ll typically need to provide tax returns, pay stubs, and proof of residence. However, this thorough vetting process often results in competitive rates for qualified borrowers.
Personal loan terms generally span 24 to 84 months, giving you flexibility in structuring your payments. While the approval process may take longer than dealership financing, the potential for lower interest rates makes this option worth considering, especially if you have excellent credit.
A HELOC provides a revolving credit line secured by your home equity, offering unique advantages for swim spa financing. This flexibility means you can borrow funds as needed and only pay interest on the amount you actually use. Variable interest rates typically range from 4% to 8% APR, making HELOCs one of the most cost-effective financing options available.
One of the most compelling aspects of HELOC financing is the potential for tax-deductible interest. When your swim spa qualifies as a home improvement that adds value to your property, the interest you pay may be deductible on your tax return. This benefit can significantly reduce the effective cost of financing, though you should consult with a tax professional to understand your specific situation.
The main considerations with a HELOC include variable rates that can change with market conditions and the fact that your home serves as collateral. You’ll also need to account for closing costs, including appraisal and title fees, though these are often offset by the lower interest rates.
Unlike a HELOC’s revolving structure, a traditional home equity loan provides a lump sum at a fixed interest rate. This option offers the stability of predictable monthly payments over terms typically ranging from 5 to 20 years. Fixed rates generally fall between 4% and 9% APR, depending on your credit profile and current market conditions.
Home equity loans share the same tax advantages as HELOCs for qualifying home improvements, potentially making the interest tax-deductible. The fixed-rate structure protects you from interest rate increases, providing payment certainty throughout the loan term.
Qualification requires sufficient home equity (usually 15-20% minimum) and strong credit. The application process is more involved than unsecured loans, typically taking 1-4 weeks due to property appraisal requirements and underwriting procedures.
For homeowners with substantial available credit, credit cards can provide immediate financing for swim spa purchases. This option works best for short-term financing or when you can take advantage of promotional offers. Standard credit card interest rates range from 12% to 25% APR, making this approach more expensive for long-term financing compared to other options.
The key to successful credit card financing lies in leveraging introductory offers. Many cards offer 0% APR for 12-18 months on new purchases, allowing you to pay off your swim spa interest-free if you can retire the debt before the promotional period ends.
Credit card purchases can also provide additional value through rewards programs. Cash back or points earned on a large purchase like a swim spa can offset some costs, though you should never let rewards influence your decision if you can’t pay off the balance quickly.
For amounts over $10,000, credit limits may become a limiting factor. Some buyers use multiple cards or work with their card issuers to temporarily increase limits for large purchases. However, this strategy requires careful planning to ensure you can manage the resulting payments.
Understanding what financing a swim spa will actually cost in monthly payments helps you plan your budget effectively. Here are realistic examples based on current market rates as of July 2025:
For a $10,000 swim spa:
For a $15,000 swim spa:
For a $25,000 swim spa:
These calculations exclude taxes, fees, and the impact of down payments, which can reduce your monthly obligation significantly. Please see your lender for more details, as these are just estimates.
Several variables influence your final monthly payment beyond the basic loan amount and interest rate. A down payment of 10-20% can substantially reduce your monthly obligation while potentially qualifying you for better rates. Loan term length creates a trade-off between monthly affordability and total interest paid over the life of the loan.
Your credit score plays a crucial role in determining your interest rate, with differences of several percentage points common between good and excellent credit. Online loan calculators can help you model different scenarios, but remember that these tools provide estimates, and your actual terms may vary based on the complete underwriting process.
The best financing choice depends on your individual circumstances, including credit profile, available equity, and risk tolerance. Dealership financing offers convenience and speed, making it ideal when you want to complete your purchase quickly. Personal loans provide flexibility and fixed rates for borrowers with good credit who prefer to shop around.
Home equity options deliver the lowest rates and potential tax benefits but require sufficient home equity and involve your property as collateral. Credit cards work best for short-term financing or when promotional rates are available.
Most financing options have minimum credit score requirements that vary by lender and loan type:
If your credit score falls below these thresholds, you may still qualify for subprime financing programs, though expect higher interest rates. Some dealers work with specialized lenders who focus on helping customers with less-than-perfect credit.
The documentation required varies by financing type, but generally includes:
Home equity financing requires additional documentation, including recent tax assessments, homeowner’s insurance information, and sometimes a formal appraisal. The more documentation you can provide upfront, the faster your approval process will typically proceed.
If you’re concerned about qualification, several strategies can improve your chances of approval and better terms:
Swim spa financing becomes even more attractive during promotional periods. Manufacturers and dealers typically offer their best deals during spring and fall sales events, when 0% APR financing for 72 months might be available to qualified buyers. These promotions can save thousands of dollars in interest costs compared to standard financing terms.
Bundle deals represent another way to maximize value, combining your swim spa purchase with installation, accessories, warranties, or maintenance packages at promotional rates. These comprehensive packages often provide better overall value than purchasing components separately.
First-time buyer incentives and loyalty customer discounts can provide additional savings opportunities. Some manufacturers offer special programs for customers who are upgrading from hot tubs to swim spas, recognizing the natural progression many homeowners make.
The key to maximizing promotional offers is timing and preparation. Have your financing pre-approved and be ready to make a decision when attractive promotional rates become available. These offers are typically time-limited and may have specific qualification requirements.
The financing application process varies by lender but generally follows these steps:
Approval timelines depend on your chosen financing method:
Having all required documentation ready can significantly accelerate the process. Pre-approval from multiple lenders allows you to compare offers and negotiate from a position of strength.
If your initial application is denied, don’t give up. Consider these alternative strategies:
Don’t accept the first financing offer you receive. Different lenders evaluate risk differently, and rates can vary significantly between institutions. Online comparison tools make it easy to check rates from multiple lenders quickly, often with soft credit pulls that don’t affect your credit score.
When comparing offers, look beyond just the interest rate. Consider fees, prepayment penalties, and total cost over the loan term. A slightly higher rate with no fees might be better than a lower rate with significant upfront costs.
Having pre-approved financing gives you negotiating power with dealers. Even if you ultimately choose dealer financing, having alternative options can help you secure better terms. Dealers may be willing to match or beat outside financing offers to complete the sale.
Cash discounts represent another negotiation opportunity. Some dealers offer price reductions for cash payments that might offset the cost of financing, especially if you can secure low-rate financing independently.
Strategic timing can result in significant savings. End-of-season sales, manufacturer promotions, and dealer inventory clearances often coincide with the best financing offers. Planning your purchase around these events requires patience but can pay off substantially.
Model year transitions also create opportunities, as dealers may offer attractive financing to move previous-year inventory. These units often have identical features to current-year models but come with better financing terms.
Can I finance a swim spa with bad credit?
Yes, many dealerships offer subprime financing programs for buyers with credit challenges. Expect higher interest rates (potentially 20-30% APR) and consider making a larger down payment to improve your terms. HFS Financial and similar specialized lenders often work with dealers to provide options for customers who might not qualify elsewhere.
How much should I put down when financing a swim spa?
While down payments aren’t always required, putting down 10-20% can improve your approval odds and reduce your interest rate. A larger down payment also lowers your monthly payment and reduces the total interest you’ll pay over the loan term.
Is dealer financing better than getting a personal loan?
Dealer financing offers convenience and sometimes promotional rates, but personal loans from banks or credit unions might offer better rates for highly qualified borrowers. The best choice depends on your credit profile and the current offers available.
What’s the typical loan term for swim spa financing?
Most swim spa loans range from 36 to 84 months, with 60-72 months being common. Longer terms reduce monthly payments but increase total interest costs. Choose a term that balances affordability with reasonable total cost.
Can I pay off my swim spa loan early?
Most reputable lenders don’t charge prepayment penalties, but always verify this before signing your loan agreement. Paying off your loan early can save significant money in interest, especially on longer-term loans.
Do swim spa loans require collateral?
Most swim spa financing is unsecured, meaning no collateral is required. The exceptions are home equity loans and HELOCs, which use your home as collateral but typically offer the lowest interest rates.
How does swim spa financing affect my credit score?
Applying for financing involves a hard credit inquiry that may temporarily lower your score by a few points. However, making timely payments on your loan will help build positive credit history over time.
Are there tax benefits to financing a swim spa?
Interest on home equity loans and HELOCs may be tax-deductible if the swim spa qualifies as a home improvement. Consult with a tax professional to understand your specific situation and potential benefits.
Financing a swim spa opens the door to year-round fitness, relaxation, and family enjoyment without requiring a large upfront investment. With proper planning and the right financing approach, you can find terms that make your swim spa affordable while protecting your financial stability. Whether you prefer the convenience of dealer financing, the competitive rates of personal loans, or the tax advantages of home equity options, there’s likely a solution that fits your needs.
Take time to compare your options, understand the complete terms, and choose financing that aligns with your long-term financial goals. With the right approach, you’ll soon be enjoying the many benefits of swim spa ownership while maintaining a payment structure that works for your budget.
Seating:
Seats
Seating:
Seats

Seating:
Seats

Start exploring the features Sundance® spas have to offer, and learn how to make spa time a focal point in your journey to share meaningful moments with the people you love.